Insolvency
Liquidation Lawyers in Melbourne
Most court liquidations start with a 21-day statutory demand. We act for directors trying to stop a winding-up, and for creditors trying to get something back out of one. On either side, the sooner you ring the more there is to work with.
- Free initial advice
- Senior lawyer on every file
- 24/7 availability
Is your company facing a winding-up, or has a company that owes you money just gone under?
Most court liquidations start with a 21-day statutory demand. We act for directors trying to stop a winding-up, and for creditors trying to get something back out of one. On either side, the sooner you ring the more there is to work with.
The winding-up clock usually starts three weeks before court
Either your own company is heading towards liquidation, or a company that owes you money has just gone into one. We act on both sides of that file, and either way the first call to 1800 130 120 is free.
If you are the director, most court liquidations in Victoria begin with a creditor’s statutory demand for a debt of $4,000 or more. From the day it is served you have 21 days to pay, settle, or apply to set it aside. Miss that window and your company is presumed insolvent, and a winding-up application in the Federal Court or the Supreme Court of Victoria usually follows. At the winding-up hearing it is then very hard to run arguments you could have run during the 21 days. Those three weeks are the part of this you can still influence, and our insolvency lawyers page goes through them in detail.
Facing a winding-up application: what you can actually do
Even after an application is filed, the company is not finished. We regularly do one of four things before the hearing: negotiate payment or settlement with the petitioning creditor, oppose the application where a genuine basis exists, seek an adjournment so the directors can appoint a voluntary administrator, or move a company with liabilities under $1 million into small business restructuring so the directors keep control while a plan goes to creditors.
Which path fits comes down to numbers: what the company owes, what it still earns, and where it stands with the ATO. We can go through those with you in one call. If the honest answer is that the company cannot be saved, a creditors’ voluntary liquidation on your timetable, with a liquidator you chose, is almost always better for you than a court appointment on a creditor’s timetable.
Choose the timing, or have it chosen for you
A planned creditors’ voluntary liquidation and a forced court winding-up can end in much the same place. The difference is that in the first one you pick the timing and the liquidator, and your conduct as a director gets explained properly instead of reconstructed by a stranger months later. Before you resolve anything we check your Director Penalty Notice exposure, your personal guarantees and your insolvent trading risk, because those three follow you out of the company. If they add up to more than you could personally carry, we cost out bankruptcy and the alternatives to it in the same conversation. You get a written view on the first call.
Directors: what follows you out of the liquidation
The company’s debts generally die with the company, but three things outlive it. Personal guarantees you signed for landlords, suppliers or financiers stay enforceable against you. The landlord is usually quickest off the mark, because a failed tenant leaves empty premises and a make-good bill behind, and that argument then runs as one of our commercial lease disputes with your guarantee sitting under it. A lockdown Director Penalty Notice for unpaid PAYG, GST or superannuation stays with you no matter what happens to the company. And if the liquidator concludes the company traded while insolvent, the court can order you to compensate creditors out of your own pocket. Our director liability page goes through each one, and we check all three on your first call.
Creditors: recovering something from a liquidation
Lodging an unsecured proof of debt is the bare minimum, and on its own it rarely gets you much. We look for the recoveries that sit outside the statutory queue: a director’s personal guarantee, a security interest registered on the PPSR, retention-of-title rights over goods you supplied, and, for unpaid employees, the Fair Entitlements Guarantee. Staff who were let go in the weeks before the appointment often ring about more than their entitlements, and where the dismissal itself was the problem the claim is wrongful termination rather than anything the liquidator handles. If a liquidator writes to you demanding repayment of an unfair preference, do not pay before getting advice. The good-faith and running-account defences defeat many of these claims, and our debt recovery lawyers run them regularly.
Statutory demand served or winding-up application filed?
The 21-day window decides what arguments your company keeps. One free call tells you whether to pay, fight, restructure or liquidate on your own terms.
What the first call covers
Call 1800 130 120 or use the form on this page. Within one conversation we tell you what clock you are on, whether the debt is genuinely disputed, your personal exposure as a director, or your realistic recovery as a creditor. Evenings and weekends included when a deadline is running.
Legal Information
Talk to a lawyer before the next step
Meet the firm
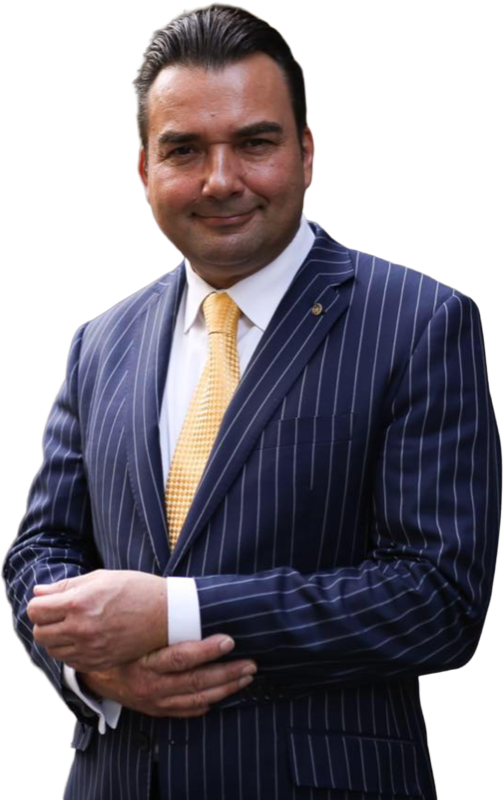
Michael Kuzilny
Founder & Principal, MK Law Group
Michael has been working in the Victorian legal system since 1986. MK Law Group acts for individuals, family businesses, and commercial clients across Melbourne, with a senior lawyer on every file from the first call.
"We take on the matters we know we can run well, and we are direct about the ones we cannot."
- Practising in Victoria since 1986
- Senior lawyer on every file from day one
- Free initial advice on every new matter
Testimonials
Real reviews from real clients
Verified client reviews appear here. Want to leave one?
Share your experienceFAQs
Frequently asked questions
-
Can a winding-up application be stopped?
Often, yes, but the earlier you call the more options exist. Before the hearing the company can pay or settle the debt, seek an adjournment to appoint a voluntary administrator or enter small business restructuring, or oppose the application. One trap: arguments the company could have raised during the 21-day statutory demand window are generally off the table at the winding-up hearing, and the court rarely gives you a second chance at them. So the work that keeps your options open happens in the first week after the demand lands, long before anyone walks into a courtroom.
-
What is the difference between voluntary and court liquidation?
A creditors' voluntary liquidation is started by the directors and shareholders when the company cannot pay its debts, and it lets you choose the timing and the liquidator. A court liquidation is forced on the company by a creditor, usually in the Federal Court or the Supreme Court of Victoria after an unpaid statutory demand. A members' voluntary liquidation is different again: it is the orderly wind-up of a solvent company.
-
What happens to me as a director once the company is in liquidation?
You lose control of the company and the liquidator starts investigating. They review the records, report to ASIC, and look for insolvent trading, unreasonable director-related transactions and unpaid tax the ATO can pursue against you through a Director Penalty Notice. Personal guarantees you signed survive the liquidation, and creditors can enforce those against you directly. If you still have any say over when the appointment happens, take advice first.
-
Who gets paid first in a liquidation?
The law sets the order and it is strict. The liquidator's costs come first, then employee entitlements such as wages and superannuation, then unsecured creditors share whatever is left. Secured creditors sit largely outside the queue and rely on their security. Most unsecured creditors see only cents in the dollar, which is why the things worth chasing usually sit outside the liquidation altogether: a personal guarantee, a registered security interest, or a claim against a director.
-
A company that owes me money is in liquidation. What do I actually do?
Lodge a proof of debt with the liquidator so you share in any dividend, then look at what sits outside the liquidation: a personal guarantee from a director, a registered security interest on the PPSR, or retention-of-title rights over goods you supplied. Employees can also claim unpaid wages, leave and redundancy through the government's Fair Entitlements Guarantee scheme. One call will tell you which of these applies to you.
-
Does liquidation clear the company's tax debt for directors?
Not always. If the ATO has issued a non-lockdown Director Penalty Notice, appointing a liquidator, administrator or small business restructuring practitioner within the 21-day notice period can remit the penalty. A lockdown DPN, issued where lodgments were more than three months late, cannot be remitted by liquidation at all, and the debt follows the director personally. It catches out more directors than anything else in this area.
- 30+
- Years in Victorian civil work
- 1,500+
- Files run end-to-end
- 4.7
- Average Google rating
- 24/7
- Free initial advice
Be in touch
Talk to a Melbourne civil lawyer today
Free first call. Honest assessment. No obligation. Reach us by phone, email, or the form below.
- marcus@mklawfirm.com.au
- 1800 130 120
- 2/212 Barkly Street, St Kilda VIC 3182