Insolvency Lawyers in Melbourne
Insolvency moves on statutory clocks. A creditor's statutory demand expires in 21 days. Voluntary administration runs in weeks. Bankruptcy lasts three years. We act for directors, creditors and individuals across Victoria.
- Free initial advice
- Senior lawyer on every file
- 24/7 availability
Free initial advice from senior lawyers
Got a statutory demand, a winding-up notice, or a DPN on your desk? Read this first.
Insolvency moves on statutory clocks. A creditor's statutory demand expires in 21 days. Voluntary administration runs in weeks. Bankruptcy lasts three years. We act for directors, creditors and individuals across Victoria.
Areas we run
MK Law represents clients across Victoria on the following matters
Insolvency runs on statutory clocks
If a creditor has served a statutory demand on your company for a debt of $4,000 or more, you have 21 days to pay it, settle it, or apply to set it aside. Miss that window and the company is presumed insolvent and a winding-up application can follow within weeks. Voluntary administration runs in about 20 to 25 business days from start to creditors’ vote. Bankruptcy lasts three years and one day, and stays on the National Personal Insolvency Index for life.
These are not soft deadlines. They are set by the Corporations Act 2001 (Cth) and the Bankruptcy Act 1966 (Cth), and the Federal Court and Supreme Court of Victoria apply them strictly. Call MK Law on 1800 130 120 today. The first call is free, including evenings and weekends for active demands.
In insolvency, the clock beats the argument. The strongest set-aside grounds and the best safe-harbour plan are worthless if you bring them on day 22. A Melbourne insolvency lawyer reading the demand on day one is the difference between options and a presumption of insolvency you can no longer rebut.
Director, creditor or facing bankruptcy: we act for all three
The word “insolvency” hides three very different problems, and we advise on all of them.
Directors of distressed companies call us when a statutory demand, a winding-up application, an ATO notice, or a major customer loss tips the company toward insolvency. The first conversation is usually about whether you keep trading, appoint a voluntary administrator, enter small business restructuring, or move straight to a creditors’ voluntary liquidation.
Creditors of failed companies call us after a customer has stopped paying, gone into administration, or been wound up. We file proofs of debt, attend creditors’ meetings, vote on deeds of company arrangement, defend unfair-preference claw-backs, and chase personal guarantees against directors. An unsecured creditor often recovers only cents in the dollar, while a secured creditor can look to its security, so the strategy is built around moving early.
Individuals facing bankruptcy call us when judgment debts, tax debts, or a personal guarantee call have made the household maths impossible. Bankruptcy is not the only answer. A debt agreement under Part IX or a personal insolvency agreement under Part X can preserve assets and avoid the three-year bankruptcy mark.
When the company is the one in distress
Most director files start with one document on the desk: the statutory demand, the winding-up application, or the Director Penalty Notice. We read it on the first call and tell you what clock you are on, whether the debt is genuinely disputed, and which path actually protects you, whether that is setting the demand aside, appointing a voluntary administrator, or entering small business restructuring. By the end of the call you have a written view and a clear next step.
Company insolvency: voluntary administration, DOCAs and liquidation
Voluntary administration is the rescue option. Directors resolve to appoint a registered voluntary administrator. From that moment an automatic moratorium stops most creditor claims, and the administrator investigates the company. Within eight business days they convene a first meeting of creditors, and within 20 to 25 business days a second meeting at which creditors vote on three options: hand control back to the directors, accept a deed of company arrangement, or move to liquidation.
A deed of company arrangement (DOCA) is a creditor-approved deal that pays out claims, often funded by the directors, a related party, or a third-party buyer. A DOCA can preserve trading, save jobs, and avoid the public stigma of liquidation. We draft, negotiate and challenge DOCAs in the Federal Court where the terms are unfair to a class of creditors. On larger matters the equivalent tool is a creditors’ scheme of arrangement, which binds dissenting creditors once the court approves it.
Liquidation takes three forms. A creditors’ voluntary liquidation is started by the directors and shareholders where the company cannot pay its debts. A members’ voluntary liquidation is a solvent wind-up. A court-ordered liquidation is started by a creditor in the Federal Court of Australia or the Supreme Court of Victoria, usually after a statutory demand goes unpaid. We act for directors defending winding-up applications and for creditors driving them. A separate path is receivership, where a secured creditor appoints a receiver under its security to realise the charged assets, which can run in parallel with an administration or liquidation.
Personal insolvency: bankruptcy and the alternatives
Bankruptcy under the Bankruptcy Act 1966 (Cth) lasts three years and one day. A creditor can issue a bankruptcy notice once a judgment debt of $10,000 or more is unpaid, and a sequestration order follows in the Federal Court of Australia or the Federal Circuit and Family Court if you fail to comply within 21 days. During the bankruptcy a trustee controls your divisible assets, your income above the indexed threshold is contributed back, and travel overseas requires the trustee’s written consent. The bankruptcy is recorded on the National Personal Insolvency Index permanently, which affects credit, some occupations, and company directorship.
It is not always the right answer. A Part IX debt agreement is available where your debts and after-tax income are below the indexed limits. It is a binding deal to pay a percentage of unsecured debts over up to five years. A Part X personal insolvency agreement is more flexible and suits higher-asset individuals who want to make a one-off settlement rather than enter bankruptcy. Both options keep you off the bankruptcy register, though they still appear on the NPII. Bankruptcy lawyers in Melbourne at MK Law will run the numbers on all three options on a first call.
Bankruptcy and liquidation are the loudest options, not always the right ones. Half the people who walk in convinced they are finished still have a debt agreement, a safe-harbour plan, or a restructuring on the table. The job is to find it before the deadline closes it off.
MK Law Group
Director duties, insolvent trading and DPNs
Section 588G of the Corporations Act makes a director personally liable for company debts incurred while the company was insolvent and the director suspected or should have suspected insolvency. Compensation orders are paid into the pool for creditors. The safe-harbour defence in section 588GA can protect directors who, from the moment they suspect insolvency, start developing a course of action reasonably likely to lead to a better outcome than immediate administration or liquidation. Safe harbour requires real documentation, tax compliance, and proper advice. It is not retrospective.
ATO enforcement of Director Penalty Notices for unpaid PAYG withholding, GST and superannuation has stepped up sharply since 2022. A non-lockdown DPN gives 21 days to put the company into administration, small business restructuring, or liquidation to remit the liability. A lockdown DPN cannot be remitted at all and the debt stays with the director. Our director liability team runs DPN responses on the day the letter lands.
Small business restructuring: the director-led alternative
The Part 5.3B small business restructuring regime, in force since January 2021, lets directors of distressed companies keep control while a registered restructuring practitioner helps put a debt-compromise plan to creditors. The company must have total liabilities under $1 million, be up to date with employee entitlements and superannuation, and have lodged all required tax returns. The practitioner has 20 business days to help draft the plan and creditors have 15 business days to vote by simple majority in value. If accepted, the plan binds all unsecured creditors and the directors keep running the company. It is the cleanest way to restructure a small trading company with a viable business hiding behind a tax debt.
When the money is owed to you
Creditors lose money two ways: by not lodging in time, and by paying back what a liquidator later claws back. We file your proof of debt, vote your interest at creditors’ meetings, and pursue any personal guarantee the directors signed. If a liquidator demands repayment of an unfair preference, we run the good-faith and running-account defences hard, because a payment received in good faith on a live trading account is often not recoverable at all.
Unfair preferences and voidable transactions
A liquidator can claw back payments made to unsecured creditors in the six months before the relation-back date. The two main tools are unfair preferences under section 588FA and uncommercial transactions under section 588FB of the Corporations Act. The creditor’s defence usually runs on the good-faith defence in section 588FG and the running-account principle, which treats a continuous trading relationship as a single net balance. Recent High Court authority has narrowed statutory set-off in preference cases, so the defence often turns on the running account. This is insolvency litigation in its own right, and we act for liquidators and creditors on both sides of it.
Builder insolvency: what homeowners can do
When a residential builder enters administration or liquidation halfway through your build, you are left with a half-finished house and a deposit you may never see again. We act for homeowners under the Domestic Building Contracts Act 1995 (Vic): claiming on domestic building insurance, pursuing directors personally where they signed guarantees, and lodging proofs of debt with the liquidator. Which insurance applies depends on the date you signed. Contracts signed before 1 July 2026 sit under VMIA policies, and contracts signed from that date sit under the first-resort Home Warranty Scheme run by the Building and Plumbing Commission. Builder liquidation is a file we run weekly.
Holding a statutory demand, a winding-up notice or a DPN?
One free call tells you which clock you are on, whether the debt is genuinely disputed, and the next step that actually protects you or your recovery.
Where we appear and what it costs
We appear in the Federal Court of Australia (where most winding-up applications and section 588 proceedings are run), the Supreme Court of Victoria, and at creditors’ meetings, ASIC examinations, and AFSA hearings. Insolvency disputes routinely spill into commercial litigation, and we run those proceedings end to end. For where insolvency sits in our wider civil practice, see our civil lawyers in Melbourne hub.
The first call is free. Beyond that, cost tracks urgency and stage. A statutory demand response, a DPN response or advice on your bankruptcy options is contained work with a clear end point. Contested winding-up proceedings, unfair-preference defences and insolvent-trading claims cost more the further they run. We tell you on that first call which of the two you are looking at.
Talk to a Melbourne insolvency lawyer today
Call 1800 130 120 or use the form on this page. If you are holding a statutory demand, a winding-up application, a DPN or a bankruptcy notice, do not wait for office hours. The deadline is the deadline.
Don't wait. Every minute counts.
Get immediate legal support
Speak with a senior insolvency lawyer today. First call is free.
1800 130 120-
Free first call
-
Confidential intake
-
Senior lawyer on every file
-
24/7 availability
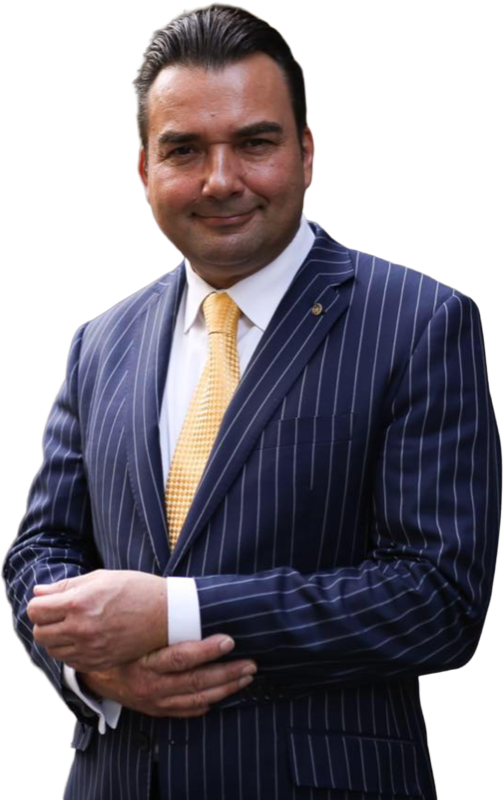
Meet the firm
Michael Kuzilny
Founder & Principal, MK Law Group
Michael has been working in the Victorian legal system since 1986. MK Law Group acts for individuals, family businesses, and commercial clients across Melbourne, with a senior lawyer on every file from the first call.
"We take on the matters we know we can run well, and we are direct about the ones we cannot."
- Practising in Victoria since 1986
- Senior lawyer on every file from day one
- Free initial advice on every new matter
Testimonials
Real reviews from real clients
Verified client reviews appear here. Want to leave one?
Share your experienceFAQs
Frequently asked questions
-
What is a statutory demand and how long do I have to respond?
A creditor's statutory demand under section 459E of the Corporations Act 2001 (Cth) gives a company 21 days to pay the debt, settle it, or apply to set it aside in the Supreme Court of Victoria or Federal Court. Miss the 21 days and the company is presumed insolvent. The court will not extend that deadline.
-
What is the difference between voluntary administration and liquidation?
Voluntary administration is a short rescue process where an independent administrator takes control of the company for about 20 to 25 business days, then creditors vote on a deed of company arrangement, a return to the directors, or liquidation. Liquidation is the wind-up itself: a liquidator realises the assets, pays claims in statutory order, and the company is deregistered.
-
What is the difference between insolvency and bankruptcy?
Insolvency is the broad term for being unable to pay your debts as they fall due, and it applies to both companies and individuals. Bankruptcy is the formal personal insolvency process for individuals under the Bankruptcy Act 1966 (Cth). Companies do not go bankrupt: they enter voluntary administration, receivership or liquidation under the Corporations Act 2001 (Cth).
-
What is insolvent trading and can I be personally liable?
Under section 588G of the Corporations Act, a director who lets a company incur debts while it is insolvent can be ordered to pay those debts personally. Compensation orders can run into the hundreds of thousands. The safe-harbour defence in section 588GA can protect directors who develop a course of action reasonably likely to lead to a better outcome.
-
What is a Director Penalty Notice?
A Director Penalty Notice is a letter from the Australian Taxation Office that makes a director personally liable for the company's unpaid PAYG, GST or superannuation. A lockdown DPN cannot be remitted by liquidation. A non-lockdown DPN gives the director 21 days to respond. Both are aggressive recovery tools and need a same-week answer.
-
Who gets paid first when a company is wound up?
The Corporations Act sets the order. The liquidator's costs come first, then employee entitlements such as wages and superannuation, then unsecured creditors share what is left. A secured creditor stands largely outside that queue and looks to its security. Most unsecured creditors recover only cents in the dollar, which is why moving early matters.
-
How long does bankruptcy last in Australia?
Bankruptcy under the Bankruptcy Act 1966 (Cth) lasts three years and one day from the date your statement of affairs is accepted by the Australian Financial Security Authority. It can be extended to five or eight years for non-compliance. The bankruptcy is recorded permanently on the National Personal Insolvency Index.
-
What is small business restructuring and who qualifies?
Small business restructuring is a director-led debt compromise process introduced in January 2021 under Part 5.3B of the Corporations Act. The company must have total liabilities under $1 million, be up to date with employee entitlements, and have lodged all tax returns. The directors stay in control while a small business restructuring practitioner helps put a plan to creditors within 20 business days, who then have 15 business days to vote.
Be in touch
Talk to a Melbourne civil lawyer today
Free first call. Honest assessment. No obligation. Reach us by phone, email, or the form below.
- marcus@mklawfirm.com.au
- 1800 130 120
- 2/212 Barkly Street, St Kilda VIC 3182